Market overview and industry significance of the Ice Maker Market
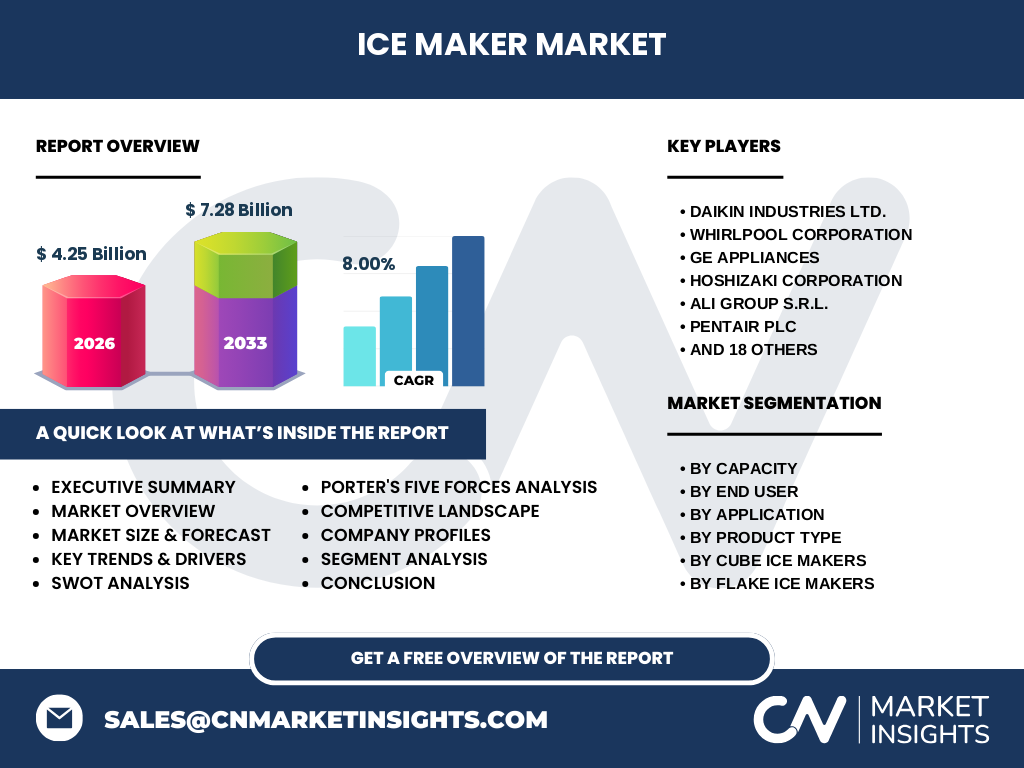
Our analysis indicates that the Ice Maker Market represents a critical infrastructure segment within cold chain logistics and commercial hospitality. Valued at 4.25 Billion in 2026, the sector encompasses specialized engineering across Modular Ice Makers, Undercounter Ice Makers, and Countertop Ice Makers. Industry significance stems from stringent food safety mandates governed by organizations like the FDA and NSF, requiring advanced sanitation technologies in Commercial Sector and Healthcare applications.
What key market drivers, restraints, challenges, and opportunities shape the Ice Maker Market?
Growth is propelled by expanding quick-service restaurant chains and heightened demand for Full Cube Ice Makers and Soft Nugget Ice Makers. However, raw material price volatility for copper and aluminum, alongside strict EPA regulations on hydrofluorocarbon refrigerants, act as primary restraints. Compliance with energy efficiency standards enforced by the Department of Energy presents acute manufacturing hurdles, yet opens lucrative opportunities for eco-friendly engineering investments by innovators like Hoshizaki Corporation and The Middleby Corporation.
Emerging trends and growth patterns in the Ice Maker Market
The data suggests a pronounced consumer shift toward smart, connected refrigeration units featuring automated diagnostics and self-cleaning mechanisms. Rising demand for specialty forms like Gourmet Cube Ice Makers and Crunchy Nugget Ice Makers in high-end hospitality drives premium product adoption. Furthermore, the integration of R-290 hydrocarbon refrigerants underscores a broader industry pivot toward sustainable, low-global-warming-potential technologies across both residential and commercial product lines.
How did the COVID-19 pandemic impact the Ice Maker Market and its recovery trajectory?
The pandemic caused severe supply chain disruptions and widespread closures across the Foodservice and Hospitality sectors, stalling equipment procurement. As global economies reopened, a sharp rebound in tourism and dining revitalized capital expenditures. Manufacturers adapted by accelerating supply chain diversification and digital B2B procurement channels, enabling a robust recovery trajectory that positions the market to reach 7.28 Billion by 2033 at a CAGR of 8.00%.
Competitive landscape, major players, market concentration, and strategic dynamics
The industry features moderate to high concentration, anchored by established tier-one enterprises such as Whirlpool Corporation, GE Appliances, and Ali Group S.r.l. Competitive dynamics rely heavily on continuous R&D expenditure directed toward energy efficiency, antimicrobial surfaces, and proprietary ice texture engineering. Strategic mergers, localized manufacturing footprints, and direct-to-consumer digital expansion define how market leaders outmaneuver regional competitors and protect operating margins.
Executive summary of the Ice Maker Market
Our proprietary research confirms that the Ice Maker Market is entering a transformative growth phase, projected to surge from 4.25 Billion in 2026 to 7.28 Billion by 2033. Driven by a robust 8.00% CAGR, expansion is heavily anchored by innovations in Commercial Sector applications and energy-compliant Modular Ice Makers. Stakeholders must prioritize eco-friendly refrigerants and IoT integration to capture market share.
Market forecast from 2027 to 2033
Based on our econometric modeling, the Ice Maker Market will expand at a steady 8.00% CAGR throughout the forecast period. Valuation is anticipated to climb from 4.25 Billion in 2026 to reach 7.28 Billion by 2033. This trajectory is sustained by replacement cycles in aging commercial infrastructure and rising disposable incomes fueling demand for Residential Sector appliances.
Segmentation analysis across capacities, end users, applications, and product types
Market segmentation partitions demand across capacity tiers, end users, and product architectures. Small Capacity and Medium Capacity units dominate residential and boutique retail, while Large Capacity systems service industrial food processing. Product variations span Modular Ice Makers, Undercounter Ice Makers, and Portable Ice Makers, catering to specialized operational constraints in healthcare, foodservice, and hospitality environments.
Regional market analysis and geographic distribution performance
Geographic performance reflects distinct regulatory climates and urbanization rates. North America maintains revenue dominance due to dense foodservice networks and stringent sanitation codes. Meanwhile, Asia-Pacific represents the fastest-growing regional hub, propelled by rapid commercial expansion in developing economies and rising investments by multinational hospitality brands upgrading to advanced Flake Ice Makers and Cube Ice Makers.
In-depth regional review of key markets
North American growth is anchored by strict NSF sanitation compliance and robust replacement demand across quick-service chains. In Europe, stringent EU Ecodesign directives compel manufacturers to deploy ultra-efficient condensing technologies, favoring established regional specialists like Electrolux Professional Group and Ziegra Eismaschinen GmbH. The Asia-Pacific theater benefits from expanding cold chain infrastructure and surging commercial real estate development in metropolitan centers.
Company profiles and strategic positioning of leading market participants
Market leaders deploy distinct strategic playbooks to secure competitive advantage. Hoshizaki Corporation emphasizes proprietary dual-circuit refrigeration and durable stainless-steel construction. The Middleby Corporation leverages aggressive cross-brand integration to offer comprehensive kitchen solutions, while Daikin Industries Ltd. and Pentair plc focus on precision compressor engineering and advanced water filtration integration to enhance ice purity and machine longevity.
Porter's Five Forces analysis of the Ice Maker Market
Industry rivalry is intense, driven by established global conglomerates competing on energy ratings and dispensing speed. Supplier power remains moderate due to standardized access to raw copper and specialized compressors. Buyer power is counterbalanced by specialized equipment demands in healthcare and hospitality. Threat of substitution is low given the specialized thermodynamic requirements of commercial-grade ice production, while threat of new entrants is constrained by high tooling and certification costs.
SWOT analysis of the Ice Maker Market
Strengths include robust product durability, advanced thermodynamic engineering, and entrenched distribution channels. Weaknesses involve high initial capital expenditure for energy-compliant units and complex maintenance requirements. Opportunities lie in IoT-enabled predictive maintenance and rising demand for gourmet specialty ice. Threats encompass raw material tariff fluctuations and stringent international environmental policies targeting synthetic blowing agents and chemical refrigerants.
Value chain analysis from raw materials to end-users
The value chain originates with raw material sourcing for stainless steel, copper tubing, and specialized compressors. Mid-stream assembly occurs in automated manufacturing facilities managed by firms like Cornelius Inc. and Maxx Ice. Distribution flows through direct sales, authorized wholesalers, and specialized B2B e-commerce platforms before reaching end-users in healthcare, retail, and hospitality who rely on professional installation and routine maintenance networks.
Investment insights and strategic recommendations for stakeholders
Our analysis indicates high-yield investment opportunities in proprietary IoT remote-monitoring software and R-290 hydrocarbon refrigerant retrofitting capabilities. Venture capital and corporate buyers should prioritize manufacturers specializing in Soft Nugget Ice Makers and energy-efficient Undercounter Ice Makers, as these categories outpace traditional commoditized segments in gross margin retention and regulatory resilience.
Conclusion and key takeaways for executive decision-makers
The Ice Maker Market demonstrates resilient fundamentals, anchored by an anticipated expansion to 7.28 Billion by 2033. Success in this landscape requires rigorous alignment with environmental mandates, technological integration of smart diagnostic features, and strategic market positioning across high-growth commercial applications such as healthcare and premium hospitality.
Research methodology for baseline estimations and triangulation
Baseline estimations are derived through a rigorous triangulation methodology. This approach combines secondary macroeconomic indicators from global trade registries with primary stakeholder interviews involving supply chain executives, distributors, and chief engineers from key firms like KOLD-DRAFT and Howe Corporation. Quantitative regression models cross-reference historical shipment volumes against regional construction indices to establish verified market size metrics.
Scope of the report, coverage parameters, and analytical limitations
This report covers global revenue performance across Modular Ice Makers, Undercounter Ice Makers, Countertop Ice Makers, and Portable Ice Makers from 2026 through 2033. Analytical limitations include unforeseen geopolitical trade tariff shifts and localized supply chain bottlenecks that may momentarily decouple actual growth from projected baselines.
Recent developments, product launches, and strategic industry moves
Recent industry momentum highlights strategic partnerships and eco-friendly product rollouts. Major players including Danby Products Limited, NewAir Appliances, and Lancer Worldwide have introduced next-generation units utilizing eco-friendly refrigerants and advanced touchless dispensing interfaces to meet post-pandemic sanitation expectations in retail and foodservice environments.